Data Brokers and Your Financial Privacy: Who Is Selling Your Information and How to Take It Back
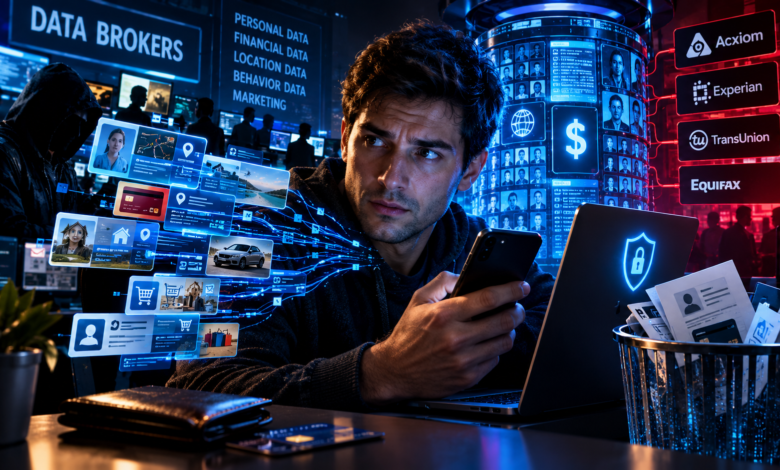
Data brokers are companies you have never heard of that collect, combine, and sell details about your life, including your income, shopping habits, location, and finances. That information fuels targeted ads, scam lists, and risk profiles, and in 2026 you finally have better tools to fight back.
- What Are Data Brokers and How Do They Get Your Information?
- What Do Data Brokers Know About Your Finances?
- How Data Brokers Put Your Money at Risk
- Your Legal Rights: What the Law Says in 2026
- How to Reduce Your Exposure: A Step-by-Step Plan
- Should You Pay for a Data Removal Service?
- How Banks and Fintech Apps Fit Into the Picture
- Frequently Asked Questions About Data Brokers and Financial Privacy
- Conclusion: You Cannot Be Invisible, but You Can Be Harder to Exploit
This guide explains how data brokers work, what they know about you, why it matters for your money, and the step-by-step actions that reduce your exposure.
What Are Data Brokers and How Do They Get Your Information?
A data broker is a company that gathers personal information from many sources and sells it or licenses it to other businesses. Most people never deal with them directly, which is exactly why the industry has grown so large. You are not their customer. You are their product.
The Different Types of Data Brokers
Not every broker does the same thing. The main types are:
- People-search sites that publish your name, address, age, relatives, and phone number for anyone to look up.
- Marketing data brokers that build profiles to help advertisers target the right audience.
- Risk and fraud-detection brokers that sell data to companies verifying identities or assessing risk.
- Financial and consumer data brokers that package spending patterns, estimated income, and purchase behavior.
- Location data brokers that buy movement data collected by mobile apps.
Some of these categories are regulated, such as credit bureaus under the Fair Credit Reporting Act. Many others operate in a gray area with far fewer rules.
Where Your Data Comes From
Brokers rarely collect information from you directly. They buy it, scrape it, or combine it from many places:
- Public records: property deeds, court filings, voter files, business licenses, and professional licenses.
- Online tracking: cookies, device IDs, and the sites and apps you visit.
- Retail and loyalty programs: what you buy, where, and how often.
- Mobile apps: location data, device details, and sometimes contact lists.
- Surveys and sweepstakes: forms that quietly include permission to share your answers.
- Other brokers: companies swap and resell data, so a single leak spreads widely.
Each piece may look harmless alone. Combined, they form a surprisingly detailed picture of who you are.
How Brokers Build Your Profile
Brokers match data points using identifiers like your email, phone number, home address, and device ID. Then they add inferences, which are guesses made by software. A broker might label you as “likely renter,” “recent new parent,” “interested in debt relief,” or “high-income household.”
Those labels may be wrong, but they still follow you. The result is a profile that can be sold thousands of times without you ever seeing it.
What Do Data Brokers Know About Your Finances?
Brokers do not usually have your exact bank balance. But they often know enough about your financial life to be useful to marketers, and to criminals.
The Financial Details That Show Up in Profiles
Common financial data points include:
- Estimated income range and net worth.
- Home ownership, home value, and mortgage details from public records.
- Credit-related signals, such as interest in loans or credit cards.
- Purchase history and spending categories.
- Life events like a divorce, a new job, a retirement, or a recent move.
- Charitable donations and political contributions.
Why This Is Different From a Credit Report
Your credit report is regulated. You have the right to see it, dispute errors, and limit who can access it. Most data broker profiles do not carry those protections. You may never learn that a broker labeled you as financially vulnerable, and you may have no easy way to correct it.
This is also why newer lending methods deserve attention. Our guide on AI credit scoring and alternative data shows how non-traditional data is entering financial decisions, which makes the quality and fairness of that data more important.
| Type of record | Who collects it | Regulated like a credit report? | Can you easily see and fix it? |
|---|---|---|---|
| Credit report | Credit bureaus | Yes | Yes, free reports and dispute rights |
| Bank and card records | Your financial institution | Partly, through banking laws | Yes, through your account |
| People-search listing | Public-record brokers | Usually no | Sometimes, through opt-out forms |
| Marketing profile | Marketing data brokers | Usually no | Rarely |
| Location history | App and location brokers | Usually no | Rarely |
| Public records | Government offices | Public by design | Limited |
How Data Brokers Put Your Money at Risk
The danger is not just annoying ads. Detailed personal data can be used against your finances in several ways.
Targeted Scams and “Sucker Lists”
Criminals buy or steal broker data to find victims who are likely to respond. Lists can be sorted by age, location, income, or past behavior, such as people who responded to earlier offers. Older adults and people in financial stress are especially targeted.
When a scammer already knows your name, address, relatives, and employer, their story sounds believable. That is the same dynamic behind the voice-clone calls we describe in our guide to deepfake scams. The more real details they hold, the more convincing the scam.
Identity Theft and Account Takeover
People-search sites often show exactly the details that security questions and identity checks rely on, such as former addresses, family members’ names, and birth years. A criminal can combine those details with stolen data to open accounts or reset passwords.
Predatory Marketing and Pricing
Financial profiles can steer which offers you see. Someone labeled as financially stressed may be shown high-interest loans, payday products, or debt settlement ads, while others see cheaper options. Regulators have also taken action against some brokers over the sale of sensitive information, such as precise location data.
Insurance, Hiring, and Other Decisions
In some cases, data from brokers may influence how companies evaluate risk or marketing eligibility. Rules vary by industry and state, and many of these uses are poorly understood by consumers. The key point is that inaccurate or outdated data can follow you without any easy way to challenge it.
Stalking and Personal Safety
Public listings with home addresses can put people at risk, including victims of abuse, people with public-facing jobs, and anyone dealing with harassment. For these people, removing data is a safety measure, not just a privacy preference.
| Risk | How broker data fuels it | Who is most exposed |
|---|---|---|
| Targeted scams | Lists of likely victims with believable personal details | Older adults, people under financial stress |
| Identity theft | Addresses, relatives, and birth details for ID checks | Everyone |
| Predatory offers | Profiles flagged as vulnerable | People with debt or low income |
| Phishing and spam | Emails and phone numbers sold in bulk | Everyone |
| Physical safety | Home addresses on people-search sites | Abuse survivors, public-facing workers |
Your Legal Rights: What the Law Says in 2026
U.S. privacy law is a patchwork. There is still no single national privacy law that covers every data broker, but several tools exist.
California’s DROP: A One-Stop Deletion Tool
California has built the most powerful option so far. Under its Delete Act, the California Privacy Protection Agency launched the Delete Request and Opt-out Platform (DROP) on January 1, 2026. Verified California residents can submit one request, and it is sent to all data brokers registered in the state, which is more than 500 companies.
Here is how the timeline works:
- Since January 1, 2026: residents can create a profile and submit a request.
- From August 1, 2026: registered brokers must access the platform at least every 45 days and process requests.
- Within 90 days: brokers must report what they did.
- Ongoing: brokers must also keep deleting new data they collect about you, not only what they hold today.
Brokers that fail to comply can face daily fines per request. The tool is free, and it is run by the state, not a private company.
Other States and Federal Laws
If you do not live in California, you still have options, though they are less convenient:
- State privacy laws: around twenty states have comprehensive privacy laws, and many give you the right to request deletion or opt out of the sale of your data. You usually must contact each company individually.
- Broker registries: some states, including Oregon, Texas, and Vermont, require data brokers to register, which helps you find who holds your data.
- Fair Credit Reporting Act: gives you rights over credit reports and certain eligibility data, including free reports and dispute rights.
- Gramm-Leach-Bliley Act: requires financial institutions to send privacy notices and lets you opt out of some sharing of your information with non-affiliated companies.
- Do Not Call and prescreened offer opt-outs: limit marketing calls and credit card offers.
Laws and deadlines change often, so check your state’s official privacy agency for the latest details.
| Tool | Who can use it | What it does | Cost |
|---|---|---|---|
| California DROP | California residents | One request to 500+ registered brokers | Free |
| State privacy rights requests | Residents of states with privacy laws | Request deletion or opt-out company by company | Free |
| Credit freeze | Everyone in the U.S. | Blocks lenders from viewing your credit file | Free |
| Prescreened offer opt-out | Everyone in the U.S. | Stops many preapproved credit and insurance mailings | Free |
| National Do Not Call Registry | Everyone in the U.S. | Reduces telemarketing calls | Free |
| GLBA opt-out notices | Customers of financial institutions | Limits some sharing with non-affiliates | Free |
How to Reduce Your Exposure: A Step-by-Step Plan
You cannot erase yourself from the internet, and trying to be perfect will burn you out. Aim to reduce the most harmful exposure first. The plan below takes a few hours spread across a week, and it will make you a much harder target.
- Check your credit reports for free and look for accounts you do not recognize.
- Place a credit freeze at each of the three major credit bureaus.
- Use DROP if you live in California, or request deletion from major brokers if you do not.
- Remove yourself from people-search sites, starting with the ones that show up when you search your own name.
- Opt out of prescreened offers and telemarketing.
- Tighten your phone and app privacy settings, especially location access.
- Use stronger logins like passkeys, and unique email addresses for financial accounts.
- Repeat every few months, because data returns.
Step 1 and 2: Lock Down Your Credit
A credit freeze is one of the strongest, simplest protections available. It stops lenders from viewing your credit file, which makes it much harder for someone to open accounts in your name. In the U.S., freezing and unfreezing is free. You will need to lift the freeze temporarily when you apply for credit yourself.
Also request your free credit reports through the official AnnualCreditReport.com site and review them for accounts or inquiries you do not recognize.
Step 3: Send Deletion Requests
If you are in California, create your DROP profile, verify your residency, and submit your request. After that, you can check the status on the platform.
If you live elsewhere, start with the biggest people-search sites and the brokers that appear most often in privacy guides. Look for links named “Do Not Sell or Share My Personal Information,” “Opt Out,” or “Your Privacy Choices.” Keep a simple spreadsheet with the date, site, and result.
Step 4: Clean Up People-Search Sites
Search for your name along with your city, and for your phone number and email. Open the first results and look for an opt-out or removal page. Many require you to confirm by email. Use a separate email address for these requests to avoid sending your main inbox even more spam.
Be patient. Some sites take days or weeks to process, and some will relist your information later.
Step 5: Cut Off the Marketing Pipeline
OptOutPrescreen.com, the official site run by the credit bureaus, lets you stop most preapproved credit and insurance offers for five years or permanently. You can also register your phone with the National Do Not Call Registry. Neither tool stops scammers, who ignore the rules, but both reduce legitimate noise and make suspicious contact stand out.
Step 6: Fix Your Phone and App Settings
Phones are a major source of broker data. Spend ten minutes on these settings:
- Set location access to “While using the app” or “Never” for apps that do not need it.
- Turn off ad tracking and reset your advertising ID regularly.
- Delete apps you no longer use.
- Review which apps can access your contacts, microphone, and photos.
Step 7: Strengthen Your Accounts
Less exposed data helps, but strong login security matters just as much. Use passkeys where available, as explained in our guide to passkeys and your bank account. Use unique passwords and a password manager for everything else. Consider a separate email address just for banking, so that a leaked shopping account does not reveal your financial login.
Step 8: Repeat on a Schedule
Brokers collect new data constantly, and many reload old profiles. Set a reminder every three to six months to search your name, check your credit reports, and renew opt-outs. Treat it like changing the batteries in a smoke detector.
| Action | Time needed | Cost | What it protects against |
|---|---|---|---|
| Review free credit reports | 20 minutes | Free | Identity theft and errors |
| Place credit freezes | 30 minutes | Free | New-account fraud |
| Submit DROP or deletion requests | 30 to 60 minutes | Free | Broad data sale and scam lists |
| Remove people-search listings | 1 to 2 hours | Free | Doxxing, identity theft, phishing |
| Opt out of prescreened offers | 10 minutes | Free | Mail theft and unwanted offers |
| Update phone privacy settings | 10 minutes | Free | Location data collection |
| Switch to passkeys and unique emails | 30 minutes | Free | Account takeover |
Should You Pay for a Data Removal Service?
Several companies offer to send removal requests for you, usually for a yearly fee. They can save time, but they are not magic.
What These Services Do Well
They monitor many broker sites, submit requests automatically, and repeat them regularly. If you are busy, or you have a safety reason to remove information, that convenience may be worth paying for.
Where They Fall Short
No service covers every broker, and removed data can come back. You also have to share personal details with the service itself, so check its privacy policy and reputation. Free options, like DROP or manual requests, work well if you can spend a few hours.
How to Choose
If you do pay, look for clear lists of covered sites, transparent pricing, reports showing results, and a policy that explains what they do with your data. Be wary of services that promise to “erase you from the internet” or demand unnecessary information.
How Banks and Fintech Apps Fit Into the Picture
Your bank is also a source of data, though a more regulated one. Banks must send privacy notices explaining what they share and with whom, and you can often limit some sharing. Read those notices at least once, and use the opt-out options they offer.
Connected finance apps raise a different question: when you link a budgeting or payment app to your bank, you are granting access to your transaction data. Our explanation of open banking and connected apps shows how that works and how to review which apps have access. Before you link any account, check what data the app collects, whether it sells or shares it, and how to revoke access.
Frequently Asked Questions About Data Brokers and Financial Privacy
Are data brokers legal?
Yes, in most cases. Data brokers operate legally in the U.S., although some states require them to register and follow rules about deletion and opt-outs. Illegal activity usually involves fraud, stalking, or misuse of the data by buyers.
How do I find out which data brokers have my information?
Start by searching your name, address, phone number, and email on search engines. Check state broker registries, and in California, use DROP to reach registered brokers at once. Privacy advocacy groups also publish lists of common brokers.
Will opting out stop all spam and scam calls?
No. Opting out reduces how many legitimate companies can buy your information, but criminals ignore these rules. Use call-blocking tools, and rely on verification habits like hanging up and calling back on a number you trust.
Does a credit freeze affect my credit score?
No. Freezing your credit does not lower your score, and it does not affect your current accounts. You only need to lift it temporarily when you apply for new credit.
Can I delete my data from every broker?
Realistically, no. New brokers appear, data gets resold, and some information comes from public records that stay public. The goal is to remove as much as you can and reduce the most sensitive exposure, such as your home address and phone number.
Is it safe to use a data removal service?
It can be, if you choose a reputable provider that clearly explains how it handles your information. Remember that you must give the service some personal details to work, so read its privacy policy first.
How often should I repeat the cleanup?
Every three to six months is a good rhythm for most people. Brokers collect new data constantly, and some relist information after you remove it.
Conclusion: You Cannot Be Invisible, but You Can Be Harder to Exploit
Data brokers turn personal information into a business, and your financial life is part of the product. You cannot disappear completely, and you do not need to. What matters is making yourself less useful to scammers and less exposed to identity theft.
Freeze your credit, use DROP if you live in California, remove yourself from the worst people-search sites, tighten your phone settings, and strengthen your logins. Then repeat the routine a few times a year.
If you remember one idea, make it this: the less a stranger can learn about you, the less convincing their lie becomes. Take thirty minutes this week to freeze your credit and search for your own name, and you will already be ahead of most people.
This article is for general information only and is not financial, legal, or privacy advice. Laws, deadlines, and company practices change, so confirm details with official sources and your state’s privacy agency before you act.